


Scout
Understand the borrower, property, program and pressure points.

Mortgage Broker
Mortgage preparation with a game-plan mindset
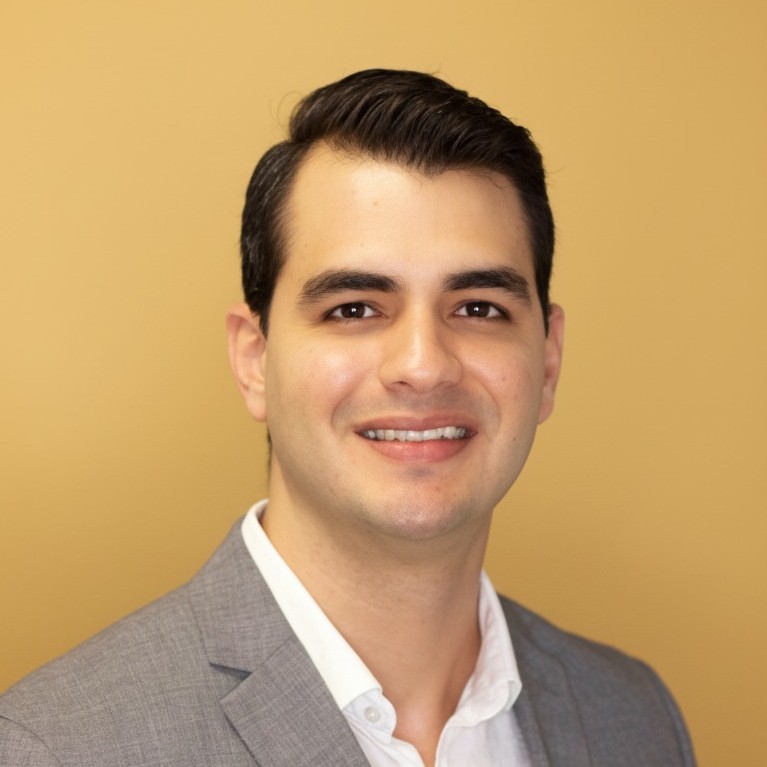
Osmail Marey combines mortgage operations discipline with the analytical habits of a devoted follower of elite basketball and European football.
Understand the borrower, property, program and pressure points.
Put the documents, reserves and timing in position.
Keep the team aligned through every handoff.
Start with the purpose of your request so the right information, documents, and next step can be reviewed.
For first-time buyers who need clarity on payment, cash to close, and what to do next.
For homeowners trying to reduce payment, consolidate debt, or use equity more intelligently.
For rental-property, DSCR, and other investor financing structures that require a documented preliminary review.
For real estate professionals who need documented borrower preparation and clearer financing communication.
Review experience, licensed states, languages, specialties, and direct contact information before choosing who will help with your mortgage review.
Review the source, context, and date before comparing individual experiences. Results vary.
“Desde el comienzo tuvo mucha paciencia y nos explicó paso a paso. Muy profesional; tuvo mucho acierto en los números desde el comienzo hasta el final del cierre. Sin dudas lo contactaré en el futuro. Gracias.”
“Osmail Marey is an outstanding mortgage professional. He provided unwavering support through every step of the process above and beyond my expectations. His knowledge, professionalism and dedication put my mind at ease and made the entire mortgage process simple and easy.”
“The professionalism and level of advice were outstanding from the day we started to the end. We needed many explanations; the agent was patient enough to answer all our questions. Grateful for the service received.”
Testimonials and reviews reflect individual experiences and may not be representative of all clients. Results vary.
Estimate principal, interest, taxes, insurance, and applicable mortgage-insurance components under clearly stated assumptions. Estimates are educational and require professional review.
Technical depth, human communication, and real context behind the broker.
Osmail Marey is a Mortgage Broker and operations leader who values preparation, timing and team communication. He studies high-level basketball and European football closely, and brings the same attention to spacing, roles and execution into the mortgage process. His role in PMA operations gives him practical insight into file movement, conditions, deadlines and the handoffs required to reach closing. The sports language is the editorial frame; every mortgage recommendation remains governed by licensing, documented facts and program guidelines.
English, Spanish
Florida Mortgage Loan Originator, NMLS #1418975. Individual profile coverage: Florida.
Continuing PMA training in mortgage guidelines, operations, underwriting, compliance and borrower communication.
Two clear programs at a time. Fast to scan. Easy to compare.
Work with Osmail Marey on purchase, refinance, and investment scenarios — with…
Work with Osmail Marey on purchase, refinance, and investment scenarios — with…
A common path for first-time buyers and credit-building situations.
Great fit for strong credit, strong assets, and clean documentation.
Multiple DPA structures exist — the details matter.
For investors focused on property cash flow (guidelines apply).
For self-employed borrowers when traditional documentation is not the best fit.
Business-purpose strategies for investors (guidelines apply).
Grant-style DPA options on Conventional and FHA (guidelines apply).
Grant-style DPA options on Conventional and FHA (guidelines apply).
Grant-style DPA options on Conventional and FHA (guidelines apply).
Repayable or forgivable structures depending on option (guidelines apply).
Repayable or forgivable structures depending on option (guidelines apply).
Repayable or forgivable structures depending on option (guidelines apply).
A distinct FHA DPA option (availability varies by state).
A distinct FHA DPA option (availability varies by state).
A distinct FHA DPA option (availability varies by state).
Miami‑Dade County down payment assistance program (eligibility rules apply).
A specialty program structure some lenders offer (guidelines apply).
A specialty program structure some lenders offer (guidelines apply).
A Non‑QM track with standard income documentation (guidelines apply).
A Non‑QM track with standard income documentation (guidelines apply).
A Non‑QM track with standard income documentation (guidelines apply).
Self‑employed income analysis using bank statements (guidelines apply).
Self‑employed income analysis using bank statements (guidelines apply).
Self‑employed income analysis using bank statements (guidelines apply).
Self‑employed income analysis using bank statements (guidelines apply).
For self‑employed borrowers where bank statements are not used (guidelines apply).
For self‑employed borrowers where bank statements are not used (guidelines apply).
For self‑employed borrowers where bank statements are not used (guidelines apply).
For self‑employed borrowers where bank statements are not used (guidelines apply).
Using verified assets to support qualifying income (guidelines apply).
Using verified assets to support qualifying income (guidelines apply).
Using verified assets to support qualifying income (guidelines apply).
Using verified assets to support qualifying income (guidelines apply).
Investor programs focused on property cash flow (guidelines apply).
Investor programs focused on property cash flow (guidelines apply).
Investor programs focused on property cash flow (guidelines apply).
Investor programs focused on property cash flow (guidelines apply).
Investor programs focused on property cash flow (guidelines apply).
For larger rentals and mixed-use when guidelines fit (business purpose).
For larger rentals and mixed-use when guidelines fit (business purpose).
For larger rentals and mixed-use when guidelines fit (business purpose).
For borrowers without a traditional U.S. credit footprint (guidelines apply).
For borrowers without a traditional U.S. credit footprint (guidelines apply).
For borrowers without a traditional U.S. credit footprint (guidelines apply).
For borrowers without a traditional U.S. credit footprint (guidelines apply).
Income documentation based on 1099s or transcripts (guidelines apply).
Income documentation based on 1099s or transcripts (guidelines apply).
Income documentation based on 1099s or transcripts (guidelines apply).
Income documentation based on 1099s or transcripts (guidelines apply).
Work verification in lieu of traditional income docs (guidelines apply).
Work verification in lieu of traditional income docs (guidelines apply).
Work verification in lieu of traditional income docs (guidelines apply).
Using multiple properties as collateral (guidelines apply).
Using multiple properties as collateral (guidelines apply).
Using multiple properties as collateral (guidelines apply).
Second-lien options for cash-out or consolidation (guidelines apply).
Second-lien options for cash-out or consolidation (guidelines apply).
Second-lien options for cash-out or consolidation (guidelines apply).
A simple map of what is commonly allowed (guidelines vary).
Baseline conforming limits (most counties in FL & TX).
Baseline conforming limits (most counties in FL & TX).
Selected counties (1–4 units). If your county differs, we confirm the exact limit.
Selected counties (1–4 units). If your county differs, we confirm the exact limit.
Selected counties (1–4 units). If your county differs, we confirm the exact limit.
Selected counties (1–4 units). We confirm the limit by property address.
We review the right scenario before you write the offer or move the file.
Program highlights are provided for educational purposes and may vary by lender, property type, and borrower eligibility. All loans are subject to underwriting approval. Rates, terms, and guidelines can change without notice.
A high‑trust platform built for experienced Mortgage Brokers. Compliance‑first systems, operational support, and technology that allows brokers to move faster without sacrificing quality. Built for professionals who want to grow production with the right infrastructure.
PMA maintains company coverage in Florida and Texas. Osmail Marey's published individual coverage is FL; other states are served only through partner referrals.
Premier Mortgage Advisors LLC is directly licensed in Florida and Texas. In other states, PMA may accept the scenario and coordinate it through an independent mortgage professional licensed in the applicable state, under a broker agreement or authorized partner arrangement when applicable. Product availability, pricing, eligibility, approval, and closing depend on the licensed partner and complete file review.
No pressure and no back-and-forth. Pick the call that fits your situation. The calendar opens in a secure Microsoft Bookings popup.
